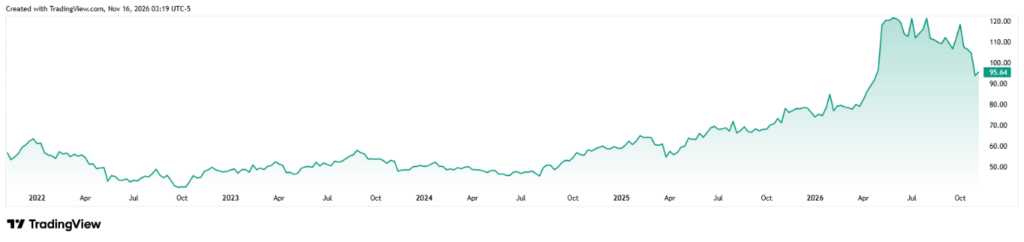
On November 12, Cisco announced that revenue for the first quarter of fiscal 2027 rose 24% year on year to a record $18.5 billion. The company raised its full-year revenue outlook, but its shares fell 6.24% to $95.64 the following trading day.* Will Cisco be able to turn growing demand for AI networking infrastructure into lasting higher profitability?
About the Company
Cisco Systems is a publicly traded American technology company headquartered in San Jose, California. It was founded in 1984 by Leonard Bosack and Sandy Lerner. Cisco supplies routers, network switches, and technologies for interconnecting data centers. It also offers cybersecurity products and tools for online collaboration and IT system monitoring. In fiscal 2026, it generated revenue of $63.3 billion, of which approximately 55% came from networking products. At the end of that period, it employed approximately 82,400 people. Its shares trade on the Nasdaq under the ticker symbol CSCO.12
Record Results Accompanied by a Share Price Drop
In the first quarter of fiscal 2027, which ended on October 24, 2026, Cisco increased revenue from $14.88 billion to a record $18.52 billion. Net income rose 59% to $4.55 billion, and diluted earnings per share increased from $0.72 to $1.14. Adjusted earnings per share reached $1.40, a year-on-year increase of 40%. According to the company, this was its fastest growth in both revenue and adjusted earnings per share in more than 15 years. Cisco released the results on November 12 after the market close. In the next regular trading session, the shares fell from $102.01 to $95.64, or 6.24%.*3
Networking Products Made Up 60% of Revenue
Networking products contributed most to growth, with revenue up 43% year on year to $11.13 billion. They thus accounted for approximately 60% of the company’s total revenue. Cisco recorded sales growth in AI infrastructure, data center switches, and enterprise networking equipment. Networking product orders rose 28%, marking the ninth consecutive quarter of double-digit growth. Total product orders rose 21%. Excluding the largest cloud customers, their growth reached 14%, so higher demand was also evident outside this group. Cybersecurity revenue rose 7% to $2.12 billion, while services revenue rose 1% to $3.85 billion.4
Cisco Expects $9 Billion from AI Infrastructure
Cisco raised its estimate of AI infrastructure revenue from the largest cloud service providers for fiscal 2027 from $7.5 billion to $9 billion. In the previous fiscal year, it reported revenue of approximately $4 billion in this area and took orders worth $9.3 billion. The difference between these figures is significant. Orders reflect demand for deliveries, whereas revenue is recognized when Cisco fulfills the relevant contractual obligations. The company also announced that in the past quarter, customers chose its technologies for three new AI projects. Two of them involve Silicon One P200 systems for interconnecting data centers, and the third involves optical components with a transmission speed of 1.6 terabits per second.5 [1]
More Expensive Memory Reduced Product Margin
Cisco’s adjusted gross margin fell year on year from 68.1% to 65.6%, as hardware revenue grew faster than software and services revenue. Higher prices of memory components also contributed to the decline in adjusted product gross margin from 67.2% to 63.7%. Meanwhile, the adjusted operating margin increased from 34.4% to a record 37.8%. These indicators capture different costs. Gross margin reflects the cost of products and services sold, while operating margin also takes into account the company’s other expenses. Adjusted operating expenses grew by only 2%, while revenue climbed 24%. Operating expenses thus made up a smaller share of revenue, and their slower growth more than offset the decline in gross margin.4
Higher Full-Year Outlook Assumes Further Profit Growth
Cisco raised its revenue outlook for fiscal 2027 from a range of $72.2 billion to $73.4 billion to $74.8 billion to $75.8 billion. The midpoint of the new range is $2.5 billion higher than in the August outlook. The adjusted earnings per share estimate moved from a range of $5.05 to $5.11 to $5.47 to $5.53. For the second fiscal quarter, the company expects revenue of $18 billion to $18.2 billion and adjusted earnings per share of $1.34 to $1.36. The adjusted operating margin outlook of 36% to 37% is below the record 37.8% from the first quarter. The higher annual estimate therefore does not assume that Cisco will repeat the record operating margin as early as the next quarter.3 [2]
Conclusion
Cisco has delivered a record quarter in which revenue growth was driven mainly by sales of networking products. The raised AI infrastructure revenue outlook of $9 billion shows how much importance the company’s management attaches to this area. However, the higher share of hardware in revenue and more expensive memory pushed down the adjusted gross margin. Even so, the adjusted operating margin reached a record 37.8%, because operating expenses grew more slowly than revenue. For investors, the key question in the coming quarters will therefore be whether Cisco can meet its higher outlook and sustain profit growth despite pressure on hardware margins.
[3]
Adam Austera, analyst at Ozios
* Past performance is not a guarantee of future results.
[1,2,3] Forward-looking statements are based on assumptions and current expectations, which may prove inaccurate, or on the current economic environment, which may change. Such statements are not guarantees of future performance. They involve risks and other uncertainties that are difficult to predict. Actual results may differ materially from those expressed or implied in any forward-looking statements.
O.Z.I. Online Zone Investment Opportunities (OZIOS) is a registered trademark of APME FX TRADING EUROPE LTD, a Cyprus Investment Firm (CIF) supervised and regulated by the Cyprus Securities and Exchange Commission (CySEC) under CIF license no. 335/17, with its registered office at Lophitis Business Center, Office 404, 4th Floor, 28 October Ave 249, Limassol 3035, Cyprus. Contracts for difference (CFDs) are complex instruments and come with a high risk of rapid financial loss due to leverage. 71.07% of retail investor accounts lose money when trading CFDs with this provider. You should consider whether you understand how CFDs work and whether you can afford to take the high risk of losing your money.
*Paid partnership
- https://en.wikipedia.org/wiki/Cisco
- https://www.cisco.com/c/dam/en_us/about/annual-report/2026-cisco-full-annual-report.pdf
- https://investor.cisco.com/news/news-details/2026/CISCO-REPORTS-FIRST-QUARTER-EARNINGS/default.aspx
- https://s21.q4cdn.com/812015656/files/doc_earnings/2027/q1/presentation/Q1-27-Earnings-Slides.pdf
- https://investor.cisco.com/news/news-details/2026/CISCO-REPORTS-FOURTH-QUARTER-AND-FISCAL-YEAR-2026-EARNINGS/default.aspx